About Flood Insurance Claims
What Are Flood Insurance Claims
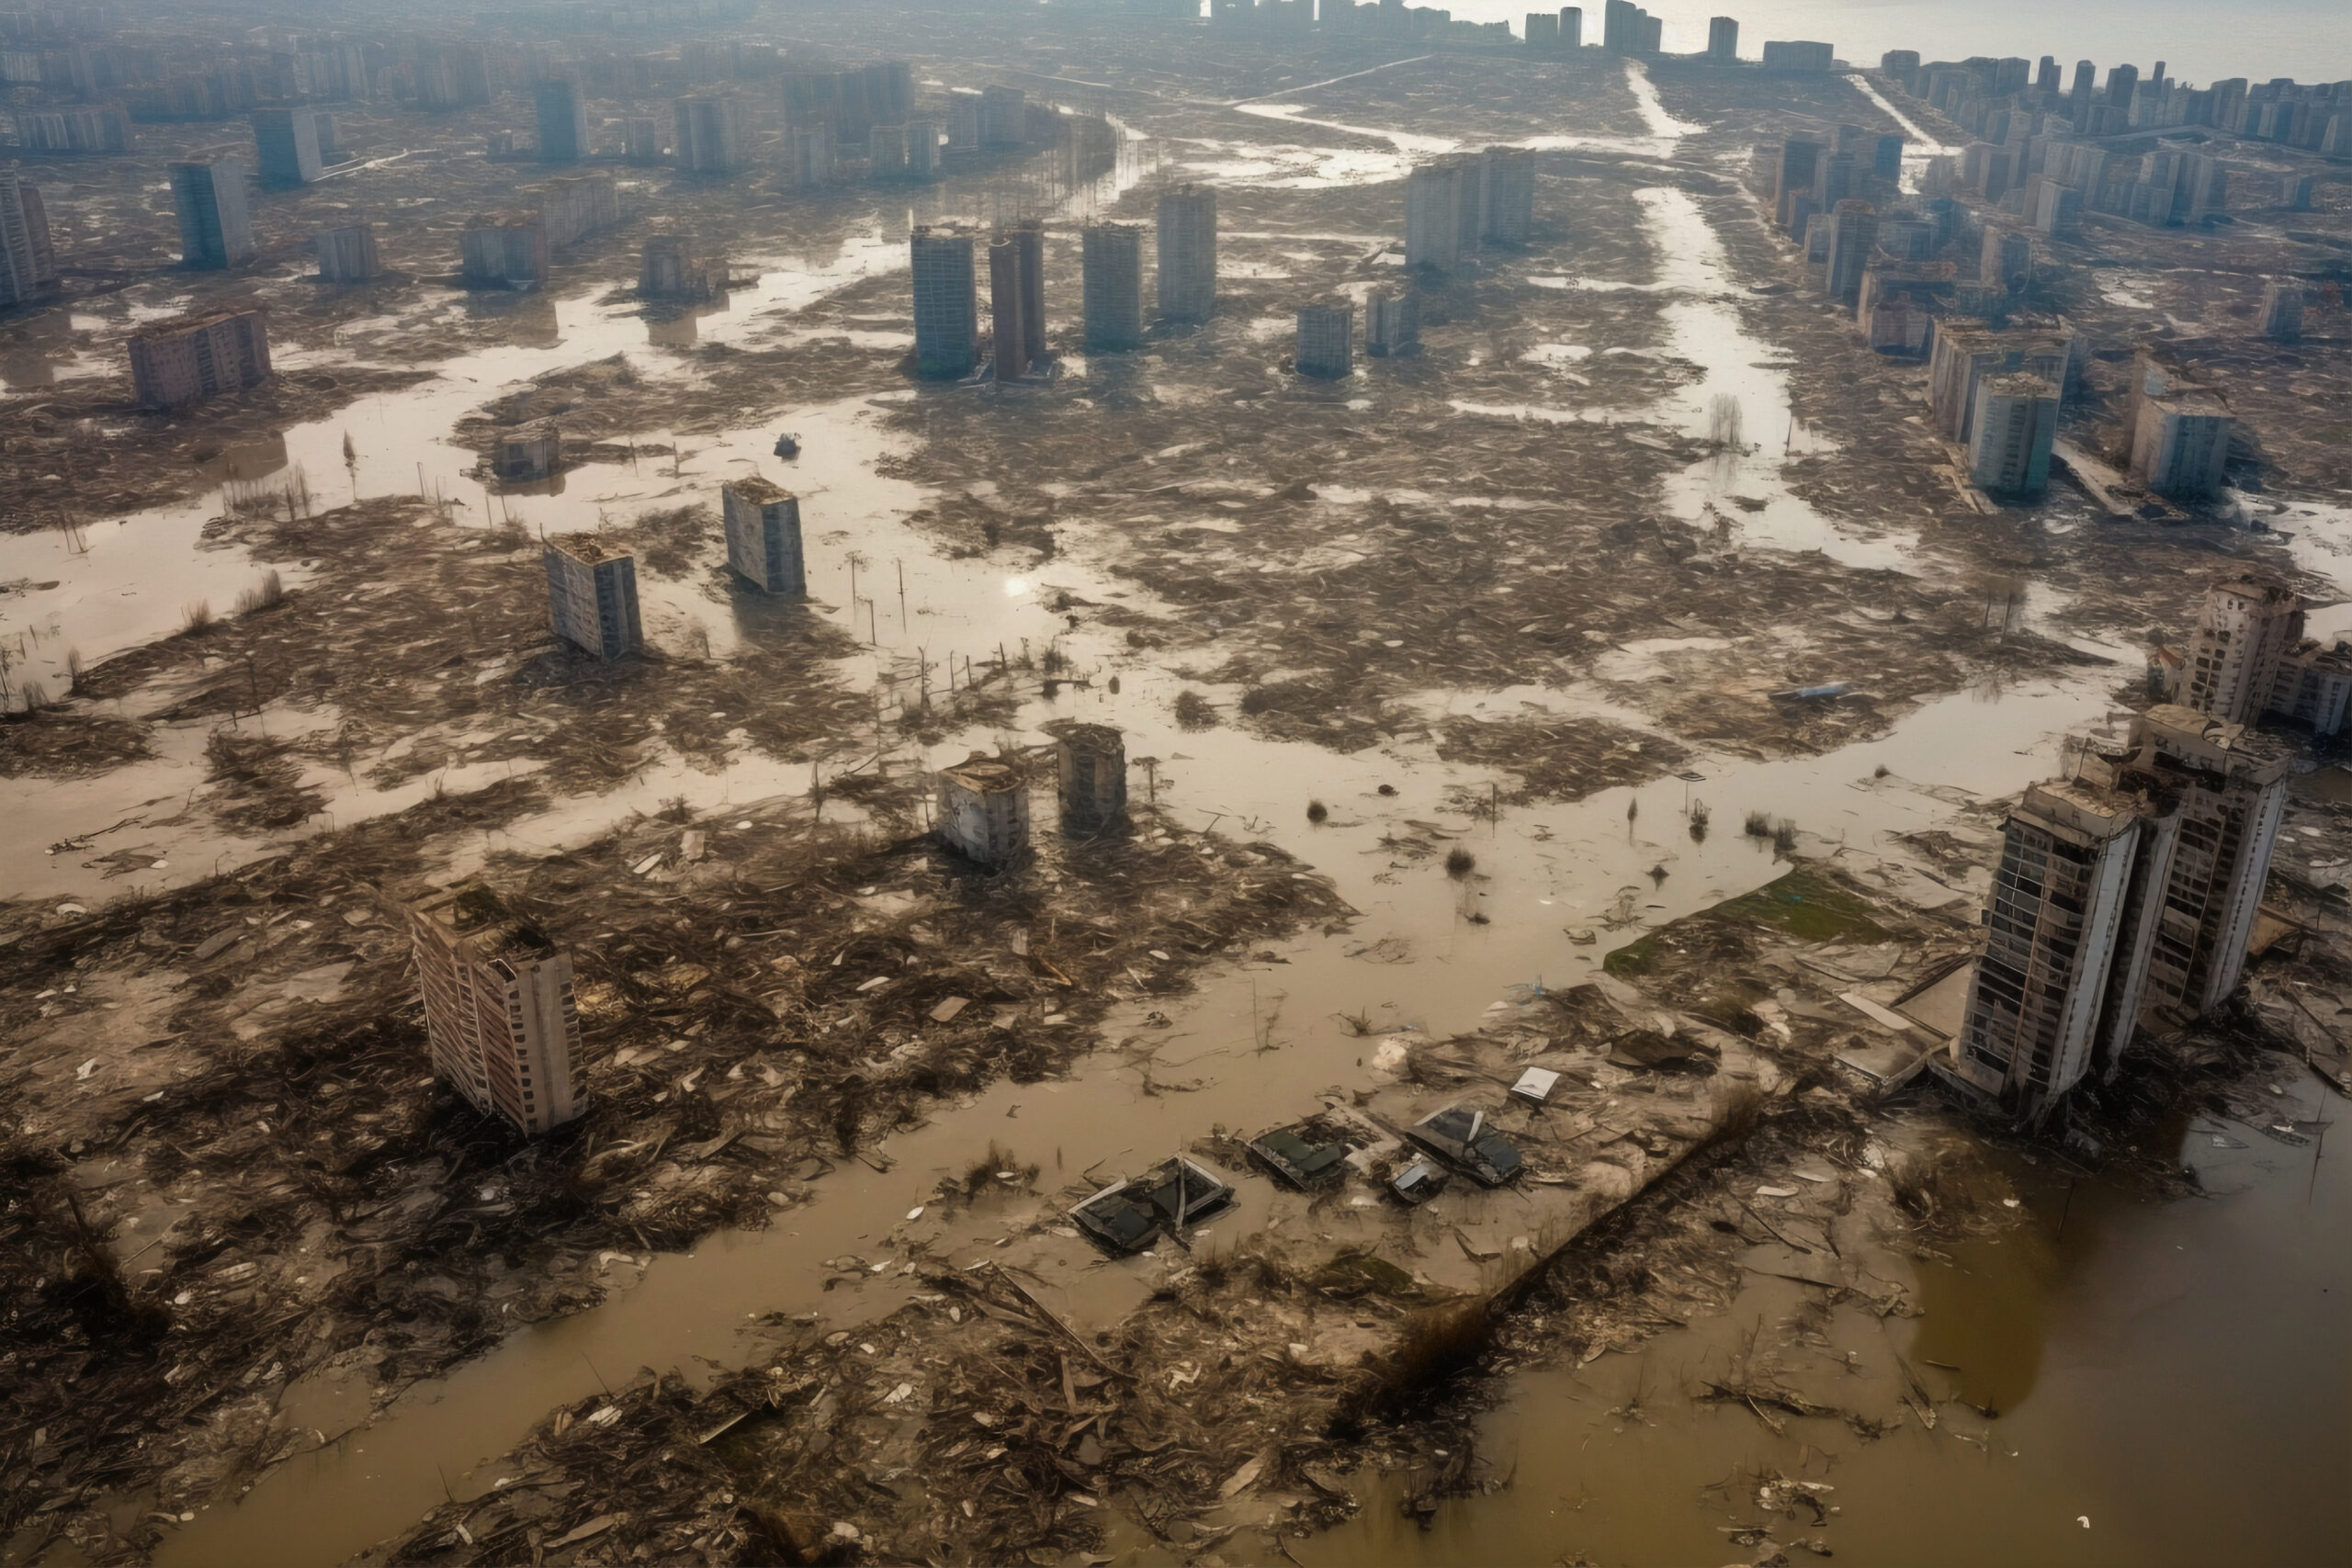
Flood insurance claims are requests made by policyholders to their insurer for financial compensation due to damage caused by flooding. Flooding occurs when water from rivers, heavy rainfall, storms, burst water mains, or surface run-off inundates a property. These claims usually fall under buildings and contents insurance, and in some areas, they may be supported by a government-backed scheme like Flood Re in the UK.
Flood damage can be extensive, affecting the structure, electrical systems, flooring, furniture, and personal possessions. Making a flood insurance claim allows property owners to repair the damage and restore their homes or businesses without bearing the full financial burden themselves.
What Do Flood Insurance Claims Typically Cover?
- Structural Repairs: Costs to repair damage to walls, floors, foundations, and electrical or plumbing systems caused by floodwater.
- Drying and Cleaning: Professional drying, cleaning, and decontamination services to prevent mould and further damage.
- Contents Replacement: Compensation for furniture, electronics, clothing, and other belongings damaged or destroyed by water.
- Alternative Accommodation: Temporary housing costs if the property is uninhabitable due to flood damage.
- Preventative Works: In some cases, policies may contribute to improvements like flood barriers or airbrick covers to prevent future damage.
How the Claims Process Works
- Flood Occurs: The property is affected by flooding, with water entering and causing damage.
- Safety and Documentation: The policyholder ensures safety, then takes photographs and detailed notes of the damage before starting any clean-up.
- Insurer is Contacted: The insurer is notified as soon as possible, and the claim is registered with initial evidence.
- Assessment and Inspection: A loss adjuster or surveyor may be appointed to inspect the property and determine the extent of the damage.
- Drying and Repairs: Once authorised, professional drying begins, followed by approved repairs and replacement of damaged contents.
- Settlement: The insurer pays for the repairs or reimburses the costs based on the policy’s terms and conditions.
Important Considerations
- Definition of Flooding: Each insurer may define flooding slightly differently; it generally refers to water from an external source entering the property.
- Policy Inclusions and Exclusions: Not all insurance policies automatically include flood cover—some properties in high-risk areas may require separate or specialist cover.
- Government Support: In the UK, the Flood Re scheme helps make insurance more affordable and accessible for properties in flood-prone areas.
- Proof and Timing: Quick action, detailed records, and compliance with insurer requirements improve the chances of a smooth claims process.
Flood insurance claims provide essential protection for property owners facing the aftermath of water-related disasters. Knowing your policy’s coverage and acting promptly can help minimise disruption and financial loss.